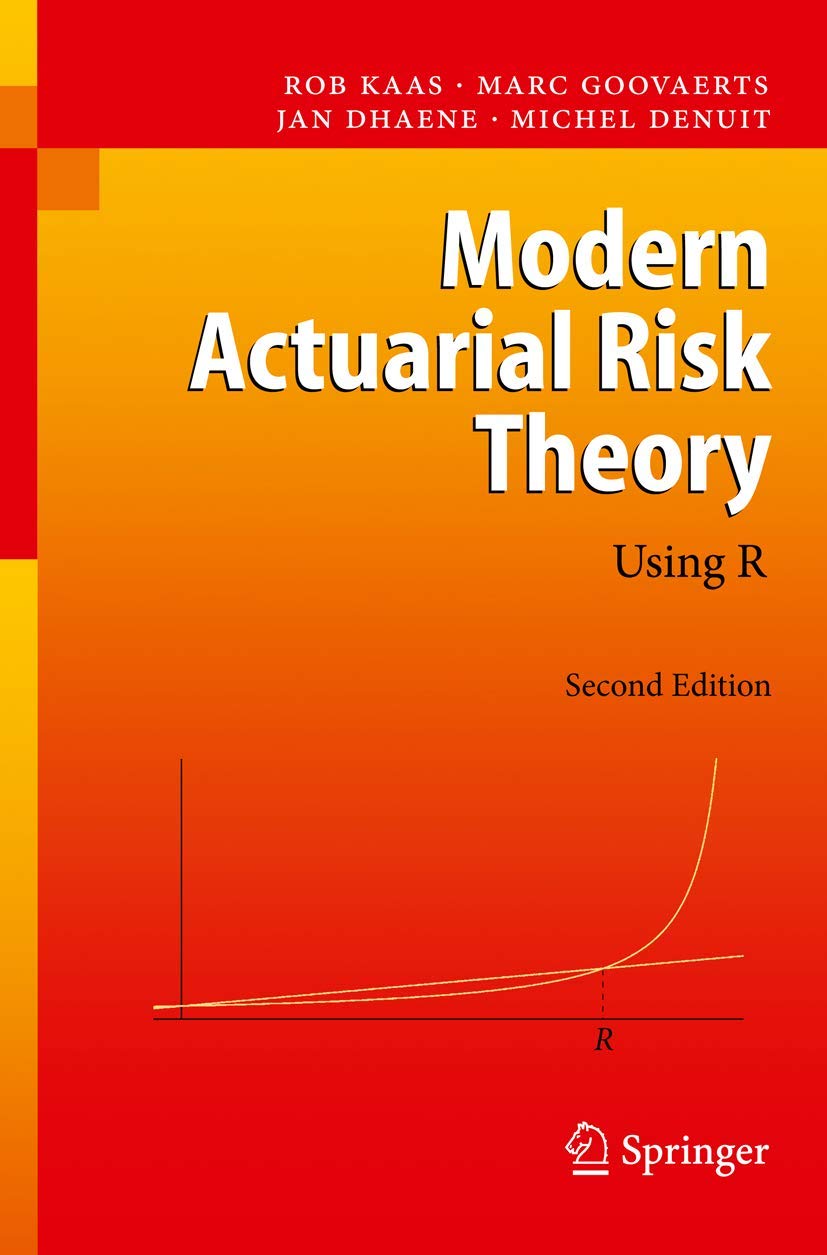
capítulo por capítulo baixar Modern Actuarial Risk Theory: Using R
por Rob Kaas
Modern Actuarial Risk Theory: Using R
Modern Actuarial Risk Theory contains what every actuary needs to know about non-life insurance mathematics. It starts with the standard material like utility theory, individual and collective model and basic ruin theory. Other topics are risk measures and premium principles, bonus-malus systems, ordering of risks and credibility theory. It also contains some chapters about Generalized Linear Models, applied to rating and IBNR problems. As to the level of the mathematics, the book would fit in a bachelors or masters program in quantitative economics or mathematical statistics. This second and much expanded edition emphasizes the implementation of these techniques through the use of R. This free but incredibly powerful software is rapidly developing into the de facto standard for statistical computation, not just in academic circles but also in practice. With R, one can do simulations, find maximum likelihood estimators, compute distributions by inverting transforms, and much more.
Procurando Modern Actuarial Risk Theory: Using R? Aqui você encontra tudo sobre este livro de Rob Kaas. Nesta página estão a descrição da obra, os detalhes da edição (382 páginas) e os formatos disponíveis para baixar: pdf, ibook, epub, kindle. Se você gosta de Livros Internacionais, Ciências Tecnológicas, Matemática, Aplicada, Teoria dos Jogos, explore também outros títulos da mesma categoria no Porto do livro Português. Veja ainda as outras obras de Rob Kaas em nosso catálogo.
Autores populares
Icon Group International (285) Publishing lmgdaw (262) Nikolay Krechet (164) Kennie B Journals (112) Riddler Books (98) Charles Nehme (95) webmarbook design (95) Mint and Cherry Notebooks (79) Iwona Makara (76) Mary Hirose (75) NAK Legal Publishing (74) Jillo Trukudo (73) Just Visualize It (69) Quick Witted Coconut (67) Talor Press (67) matlasor Sticker's (64) Miller Sye (63) Moonpeak Library (63) Ondrej Sarek (63) Roggie Clark (63)Principais publicadores
Forgotten Books Independently published Routledge Dover Publications CRC Press Taschen Princeton University Press Wiley Oxford University Press Springer Cambridge University Press Kessinger Publishing Thames & Hudson Gale, U.S. Supreme Court Records Bloomsbury Academic O'Reilly Media Rizzoli International Publications Hal Leonard Publishing Corporation Tuttle Publishing Editorial Tirant lo Blanch