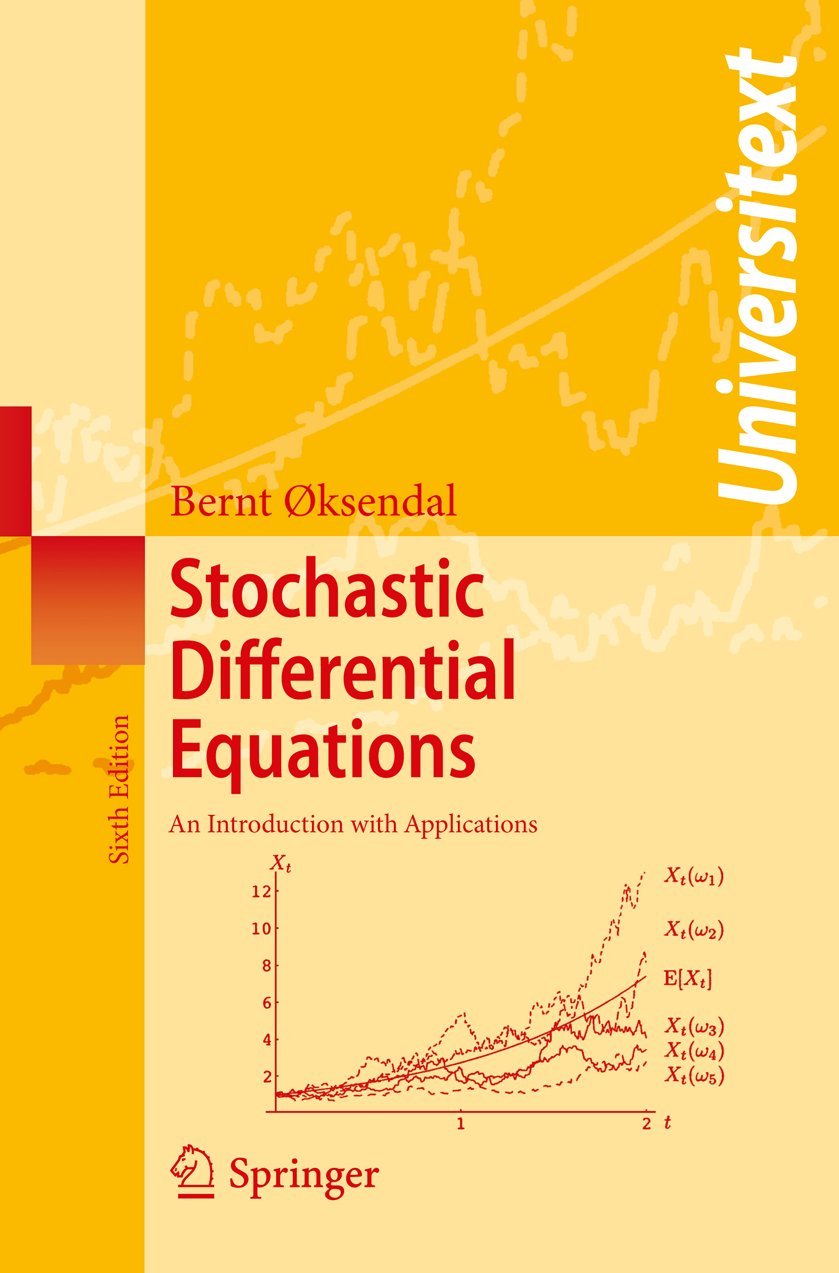
capítulo por capítulo baixar Stochastic Differential Equations: An Introduction with Applications
por B. K. Ksendal
Stochastic Differential Equations: An Introduction with Applications
This book gives an introduction to the basic theory of stochastic calculus and its applications. Examples are given throughout the text, in order to motivate and illustrate the theory and show its importance for many applications in e.g. economics, biology and physics. The basic idea of the presentation is to start from some basic results (without proofs) of the easier cases and develop the theory from there, and to concentrate on the proofs of the easier case (which nevertheless are often sufficiently general for many purposes) in order to be able to reach quickly the parts of the theory which is most important for the applications. For the 6th edition the author has added further exercises and, for the first time, solutions to many of the exercises are provided. This corrected 6th printing of the 6th edition contains additional corrections and useful improvements, based in part on helpful comments from the readers.
Procurando Stochastic Differential Equations: An Introduction with Applications? Aqui você encontra tudo sobre este livro de B. K. Ksendal, publicado por Springer. Nesta página estão a descrição da obra, os detalhes da edição (379 páginas) e os formatos disponíveis para baixar: pdf, ibook, epub, kindle. Se você gosta de Livros Internacionais, Ciências Tecnológicas, Matemática, Aplicada, Equações Diferenciais, explore também outros títulos da mesma categoria no Porto do livro Português. Veja ainda as outras obras de B. K. Ksendal em nosso catálogo.
Autores populares
Icon Group International (285) Publishing lmgdaw (262) Nikolay Krechet (164) Kennie B Journals (112) Riddler Books (98) Charles Nehme (95) webmarbook design (95) Mint and Cherry Notebooks (79) Iwona Makara (76) Mary Hirose (75) NAK Legal Publishing (74) Jillo Trukudo (73) Just Visualize It (69) Quick Witted Coconut (67) Talor Press (67) matlasor Sticker's (64) Miller Sye (63) Moonpeak Library (63) Ondrej Sarek (63) Roggie Clark (63)Principais publicadores
Springer Forgotten Books Independently published Routledge Dover Publications CRC Press Taschen Princeton University Press Wiley Oxford University Press Cambridge University Press Kessinger Publishing Thames & Hudson Gale, U.S. Supreme Court Records Bloomsbury Academic O'Reilly Media Rizzoli International Publications Hal Leonard Publishing Corporation Tuttle Publishing Editorial Tirant lo Blanch