Descrição do livro
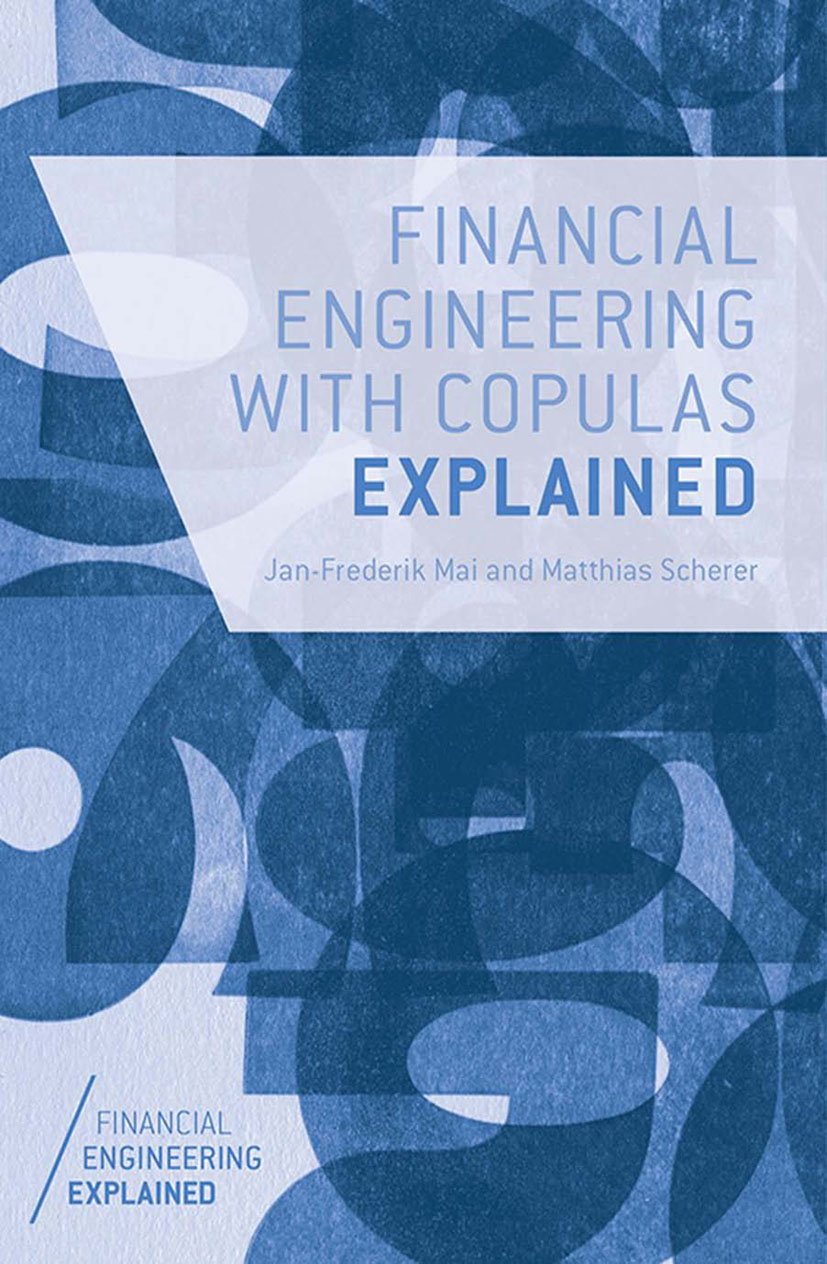
This is a succinct guide to the application and modelling of dependence models or copulas in the financial markets. First applied to credit risk modelling, copulas are now widely used across a range of derivatives transactions, asset pricing techniques and risk models and are a core part of the financial engineer's toolkit.
Isbn 13 :9781137346315
Encadernação :Kindle
Edição Financial Engineering with Copulas Explained (Financial Engineering Explained) (English Edition):2014ª
Livros recentes
Autores populares
Unknown Author (194) Barrett Williams (163) ChatGPT ChatGPT (122) Сергей Каледин (100) Lyudmil Tsvetkov (95) Sharifa McFarlane (92) Kingston Publishing (76) YouGuide (52) animarueaidezain (49) Rodrigo B Santos (48) Nikolay Krechet (46) Hayden Van Der Post (45) Coins and More (42) Evgeniia Naumchenko (40) SHIZUOKANOSORATETSU (40) Manoj Palwe (39) Various (39) Clayton Louis Turnage (38) keieisyakentoushikaken (37) Valet WorkShop (37)Livros relacionados