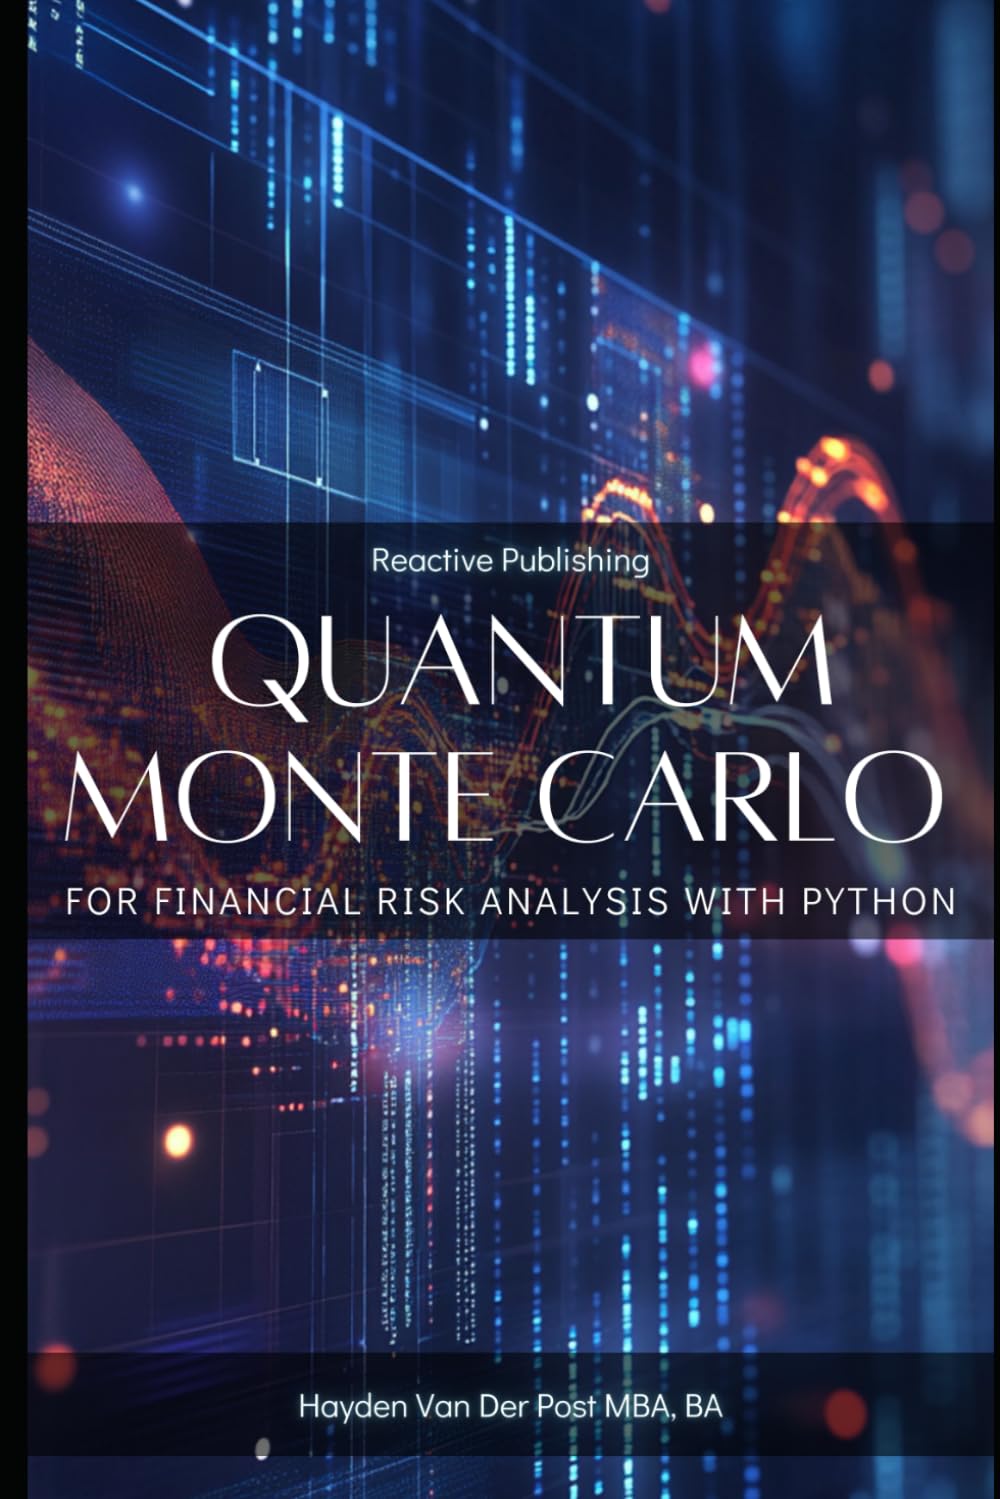
Quantum Monte Carlo for Financial Risk Analysis with Python pdf
por Hayden Van Der Post
Descrição do livro
Reactive Publishing In the rapidly evolving world of quantitative finance, traditional Monte Carlo simulations often struggle with computational inefficiencies and convergence limitations. Quantum Monte Carlo (QMC) methods offer a powerful alternative, leveraging quasi-random sequences, variance reduction techniques, and quantum-inspired algorithms to achieve faster and more accurate financial risk analysis. This book provides a practical, hands-on guide to implementing Quantum Monte Carlo techniques in Python, bridging the gap between theoretical finance and real-world computational strategies. Readers will explore advanced stochastic modeling, portfolio risk management, and derivative pricing using cutting-edge QMC techniques. Introduction to Quantum Monte Carlo – Understanding how QMC differs from traditional Monte Carlo methods in finance Whether you're a quantitative trader, risk analyst, hedge fund researcher, or financial data scientist, this book provides theoretical depth and practical implementation to help you stay ahead in modern computational finance.
Quantum Monte Carlo for Financial Risk Analysis with Python: Advanced Stochastic Methods for Portfolio Optimization and Derivatives Pricing
Quasi-Random Sequences & Low-Discrepancy Methods – Sobol, Halton, and Faure sequences for enhanced financial modeling
Variance Reduction Techniques – Antithetic sampling, importance sampling, and stratified sampling in QMC
Applications in Portfolio Optimization – Using QMC for risk-adjusted asset allocation and VaR (Value at Risk) calculations
Derivative Pricing with QMC – Accelerating option pricing models, Greeks calculation, and exotic derivatives pricing
Python Implementation & Code Optimization – Hands-on tutorials with NumPy, SciPy, JAX, and TensorFlow for efficient computation
Autores populares
Icon Group International (285) Publishing lmgdaw (262) Nikolay Krechet (164) Kennie B Journals (112) Riddler Books (98) Charles Nehme (95) webmarbook design (95) Mint and Cherry Notebooks (79) Iwona Makara (76) Mary Hirose (75) NAK Legal Publishing (74) Jillo Trukudo (73) Just Visualize It (69) Quick Witted Coconut (67) Talor Press (67) matlasor Sticker's (64) Miller Sye (63) Moonpeak Library (63) Ondrej Sarek (63) Roggie Clark (63)